The digital banking landscape in Malaysia is barely out of its infancy, yet the cracks are already beginning to show. In a surprising turn of events, KAF Digital Bank, one of the five consortiums awarded a coveted digital banking license by Bank Negara Malaysia (BNM), is facing a significant restructuring. Following the abrupt departure of its CEO and mounting financial losses, reports indicate that KAF Investment Bank is exploring the sale of its digital arm less than a year after its public launch.
Leadership Changes
The first domino to fall was the exit of Rafiza Ghazali. A well-respected figure in the Malaysian fintech space and the former CEO of Cradle Fund, Rafiza had led the bank since its inception in 2022, steering it through the rigorous “operational readiness review” required by the central bank. She officially vacated her post on 31 January 2026 to join Fasset as Managing Director for Consumer Banking.
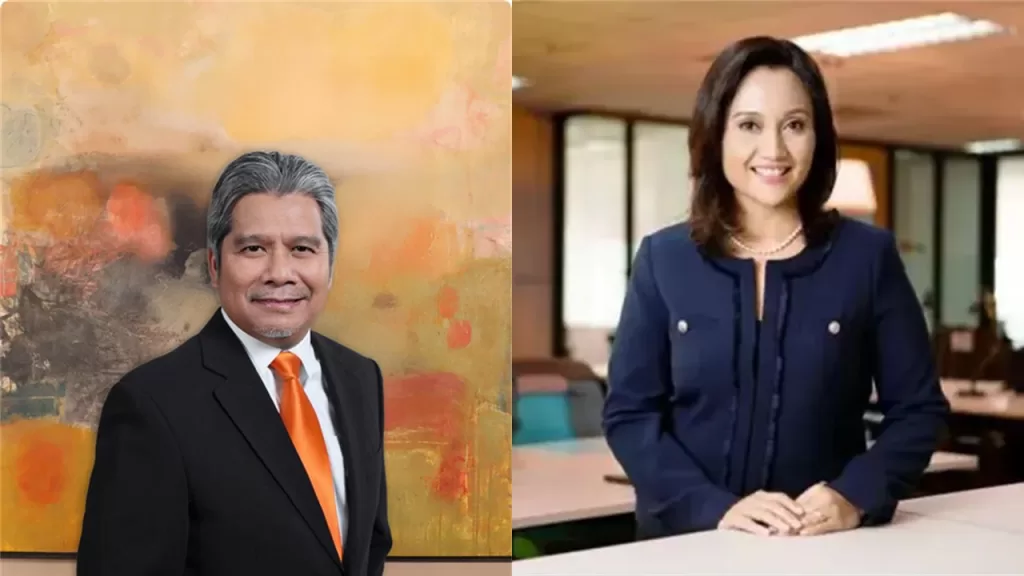
In her wake, the bank has appointed Suzaini Mukhtar as the new Chief Executive Officer. Suzaini is an industry veteran with over two decades of experience, having held senior roles at Bank Simpanan Nasional (BSN), Standard Chartered, and HSBC. While his resume is robust, he steps into the role during a turbulent period where the bank’s future ownership is an open question.
The “For Sale” Sign is Up
According to industry sources, KAF Investment Bank—which owns a controlling 84% stake in the digital bank—is actively looking to offload its interest. The reported asking price is around RM80 million (approx. USD 18 million) for a complete sale. This valuation has raised eyebrows, as it is relatively modest given the scarcity and potential value of a full digital banking license in a regulated market like Malaysia.
The bank is currently operated by a consortium that includes well-known Malaysian tech names like Carsome, MoneyMatch, Jirnexu (the parent company of RinggitPlus), and StoreHub, each holding a small 4% stake. It is unclear if these partners would exit alongside KAF or remain as minority shareholders under a new owner.
Mounting Losses and the “AI Tax”
The motivation behind the potential sale appears to be financial sustainability. Like all new digital banks, KAF has been burning cash to build infrastructure and acquire customers. For the financial year ended 30 June 2025, the bank reported a net loss of RM44.4 million, which has continued to widen into the first quarter of 2026.
While losses are expected in the early years of any startup, the pressure is compounded by the rising cost of compliance and technology. As noted by industry observers, the cost of running a secure, AI-driven banking stack has skyrocketed, creating a high barrier to entry that KAF Investment Bank may no longer be willing to fund alone.
Regulatory Hurdles
Any sale, however, is not as simple as signing a check. The digital banking licenses issued by BNM come with strict conditions. One key clause is the “Foundational Phase”—a period of three to five years during which the bank must demonstrate viability and maintain an asset threshold below RM3 billion.
Crucially, BNM regulations typically restrict significant changes in shareholding during this initial phase to ensure stability. KAF would need explicit approval from the central bank to sell its controlling stake. BNM will scrutinize any potential buyer to ensure they have the financial muscle and technical capability to deliver on the original mandate: serving the underserved and unbanked segments of Malaysia.
What This Means for Users
For now, KAF Digital Bank continues to operate as normal. Customers can still access their accounts, and the bank’s app remains functional. However, this development serves as a reality check for the Malaysian digital banking hype cycle. It signals that winning a license was the easy part; building a sustainable, profitable bank in a competitive market dominated by giants like Maybank and CIMB is a much harder challenge.
As 2026 unfolds, all eyes will be on whether a new buyer steps in to rescue the project or if KAF becomes the first casualty of Malaysia’s digital banking experiment.